This week in UK data centres:
Nebius and Vantage announce the first commercial capacity commitment in the South Wales AI Growth Zone — a policy designation turns into contracted racks
The SDC M40 Campus near Beaconsfield enters the NSIP process — 300MW of gas-powered AI data centre on a former landfill site next to the M40
Ofgem’s Data Centre Commitment Fee consultation continues to attract legal and industry analysis — the £712,500 per MW figure is generating real commercial scrutiny
The South Wales AI Growth Zone gets its first commercial commitment.
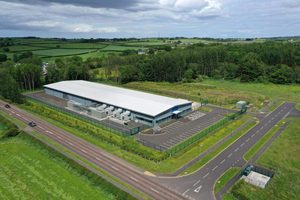
Vantage Data Centers and Nebius announced on 13 August 2026 an agreement to deploy high-density, Nvidia-powered AI infrastructure at Vantage’s CWL1 campus in Newport, Wales. The deployment represents the first announced commercial capacity commitment in the South Wales AI Growth Zone.
The size of the deployment was not disclosed, but will be based on Nvidia’s DSX AI factory reference design. Nebius will lease high-density capacity at CWL1 to support AI training, inference, agentic AI, and enterprise AI workloads. CWL1 has operated since 2010 and is one of Europe’s largest data centre campuses. Vantage plans to deliver more than 1GW of AI-ready capacity across Newport, Bridgend, and Bro Tathan as part of a multi-billion-pound investment in South Wales.
Nebius itself has been scaling aggressively across Europe — a $10 billion, 310MW AI factory in Finland, a $27 billion AI cloud infrastructure deal with Meta, and a £1.7 billion UK expansion commitment across four sites including Kao Data. The Newport deployment adds to that run of commitments, with the company’s general manager for EMEA noting the UK as one of the places where AI is being built, deployed, and adopted by startups, enterprises and the public sector.
The commercial significance of the Newport announcement goes beyond the individual deployment. South Wales now has a live anchor tenant in its AI Growth Zone. That changes the investment case for other developers building in the zone — and provides the clearest evidence yet that AI Growth Zone designation can attract committed demand, not just planning applications.
Sources: Vantage Data Centers — Vantage and Nebius expand UK AI infrastructure in South Wales AI Growth Zone | Data Centre Dynamics — Nebius to lease data center capacity from Vantage in Newport, Wales | Capacity Global — Nebius to deploy AI capacity at Vantage’s Newport campus
A 300MW gas-powered data centre on a former landfill next to the M40 enters the NSIP process.
The SDC M40 Campus — backed by investment firm SDC Capital Partners and utilities company Veolia — proposes three 100MW data centre buildings, an energy centre, and auxiliary buildings on a Veolia-owned site between Beaconsfield and Gerrards Cross, currently a former landfill for inert building waste. The Planning Inspectorate published a Scoping Opinion for the project on 9 June 2026.
Both the data centre and the on-site gas energy centre have been given direction to be treated as NSIPs. This does not mean the project has been approved — the NSIP designation routes the consenting decision to the Secretary of State rather than the local planning authority, but the project still requires a full Development Consent Order process. Data centres became eligible for the NSIP regime following the Infrastructure Planning Regulations 2026 in January.
The project illustrates two things simultaneously. First, the NSIP route working as intended — a large-scale project that would have faced significant local planning complexity is being routed through a centralised consenting process. Second, the continuation of the gas pattern for large data centre projects in grid-constrained locations. Beaconsfield and Gerrards Cross sit in the heart of the most congested data centre corridor in the UK. A gas turbine is not the preferred outcome. It is the only credible option for a project that needs power on a deliverable timeline.
The SDC M40 Campus is the fourth large UK data centre project this year to propose on-site gas generation as the primary power solution, alongside Bedfordshire, Thames Valley Park, and the Devon proposal. The pattern is structural rather than exceptional.
Sources: Planning Inspectorate — SDC M40 Campus NSIP project page | Data Centre Dynamics — UK Government to decide whether to approve 300MW data center in Buckinghamshire
The Ofgem commitment fee consultation is generating serious commercial and legal scrutiny.
Ofgem’s consultation on the Data Centre Commitment Fee — open until 16 September 2026 — is attracting significant legal and commercial analysis from the sector. The consultation comes as demand for electricity connections continued to grow, with the grid connection queue growing 460% in the first half of 2025 alone, leading to years-long waiting times.
The fee is proposed at between £237,500 and £712,500 per megawatt — 2.5% to 7.5% of average data centre capex per MW, with average capex assumed at £9.5m per MW. The fee is paid when accepting a connection offer, refunded on energisation, and forfeited on exit. It functions as a performance bond rather than a cost — the commercial exposure for a committed project is the opportunity cost of the locked capital, not the fee itself.
The milestone requirements that accompany the fee may be more significant than the financial exposure for speculative projects — demonstrating financial capability, commercial maturity, and procurement activity at defined intervals. Projects that cannot meet these milestones lose their queue position regardless of whether they can afford the fee.
Ofgem has noted that there are 100GW of data centre projects in the queue, and clearly not all of them are going to be able to connect to the grid. Projects that cannot will need to find alternative methods of power supply. The commitment fee is the mechanism designed to force that reckoning before speculative projects consume further queue capacity.
Sources: Capacity Global — UK energy regulator promises power crackdown for data centres | Herbert Smith Freehills Kramer — UK Grid Connections Reform: Ofgem’s Data Centre Fee Proposals | JD Supra — UK Grid Connections Reform: Ofgem Proposals for New Data Centre Commitment Fee
The week in one line: South Wales became the first UK AI Growth Zone to record a commercial capacity commitment, a 300MW gas-powered data centre on former landfill next to the M40 entered the NSIP process, and the Ofgem commitment fee consultation is generating serious legal and commercial scrutiny that is clarifying what the fee actually means in practice for committed projects.
Armason tracks infrastructure signals across the UK and European data centre market. For site availability, grid intelligence, or pipeline advisory, visit armason.co.uk.
Related reading
UK Data Centre Intelligence — Week Commencing 28 July 2026
AI Growth Zones UK: what they actually mean for data centre developers and grid access
Data centre sites outside London: where power is actually available in the UK in 2026
Ofgem first ready first connected: what the grid queue reform means for data centre developers